You already know what your business needs. Maybe it’s a second truck, a new piece of equipment, or a little extra breathing room during a slow season.
The trickier part is figuring out which financing fits the job.
Here’s how to get a small business loan in 2026, step by step, with advice straight from our business lending team.
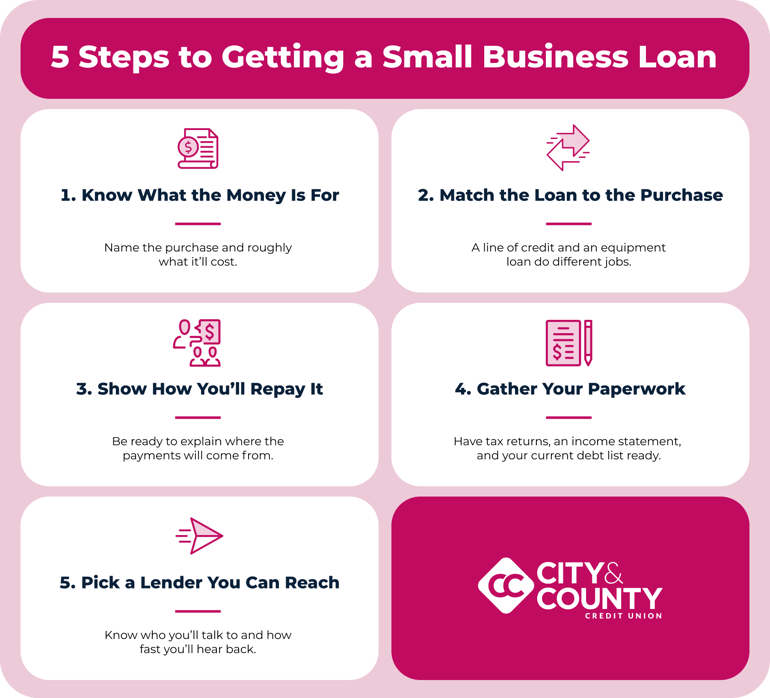
Step 1: Know What You Need the Money To Cover
Before you compare loan types, get specific about what you're paying for. You don't need to know a term loan from a line of credit to talk to a lender. Start with what the money is for and roughly how much you’ll need.
“A new skid steer before spring” or “enough to cover payroll through a slow January” gives us something to work with.
 Step 2: Match the Financing to the Job
One of the most common mistakes our business lending team sees is using a line of credit to buy equipment or a vehicle.
A line of credit is handy for inventory and operating costs. Use one to buy a mower or work truck, though, and you could spend years paying it off at a higher cost than a loan built for that purchase. (That mower won't feel nearly as new by then.)
The right loan depends on what you're financing:
| Option | Best For | How It Works at CCCU |
| Term and equipment loans | One large purchase, like a truck or a machine | Set payments over about as long as the purchase will last |
| Business lines of credit | A bill that comes due before a client pays you | Pay interest only on what you draw, and you can borrow again as you pay it down |
| SBA loans | Longer terms on bigger needs | Set payments over a longer term than a typical business loan |
| Business credit cards | Day-to-day spending like supplies and fuel | Pay the full balance each month, or over time with interest |
At CCCU, business vehicle loans run up to seven years, a Business Ready Reserve covers up to $5,000 if you overdraw your business checking, and business credit cards carry no annual fee. We also work with SBA partners on 7(a) and 504 loans.
Buying or expanding a building? That’s where commercial real estate loans come in.
Step 3: Show How You'll Repay the Loan
At CCCU, we don't look up business credit at all. Here's what we look at instead:
-
Cash flow: Whether the business brings in enough to cover the payments.
-
Collateral: What's securing the loan, like the equipment or property you're buying.
-
Your personal debt: Your credit score matters, and so does how much you owe.
Before you apply, be ready to answer one simple question: How will the payments get made?
If the business already brings in steady income, that's your answer. Just getting started? A paycheck from a day job you're keeping can help show where repayment will come from.
 Step 4: Get Your Paperwork Together
If your business already has an account with us, here’s what our lending team generally asks for:
- Two to three years of filed tax returns for the business and each owner
- A year-to-date income statement for the business
- A list of the debt the business carries now
- Personal financial statements from each owner for larger loans (we'll send you the template)
Those documents help us see what’s coming in, what you already owe, and whether there’s room for a new payment. Not a member yet? Opening a business account comes first.

Step 5: Choose a Lender You Can Reach
Rates are the obvious place to start, and because CCCU is member-owned and not-for-profit, our earnings go back to members as competitive loan rates. It's worth asking any lender a few other questions, too.
Ask who you’ll work with, how quickly you can expect an answer, and whether someone will help you choose the right loan.
Our Twin Cities Business Services team is small on purpose, with more than 30 years of business lending experience. You get a direct phone number and email for the people handling your request, and they'll already know your business.
Whether you're financing a piece of equipment or planning something bigger, you'll get the same conversation and the same attention.
 Talk Through Your Next Business Move With CCCU
If the business needs a second truck, new equipment, or some breathing room before the slow season, our business lending team can talk through the financing and how you'll repay it.